


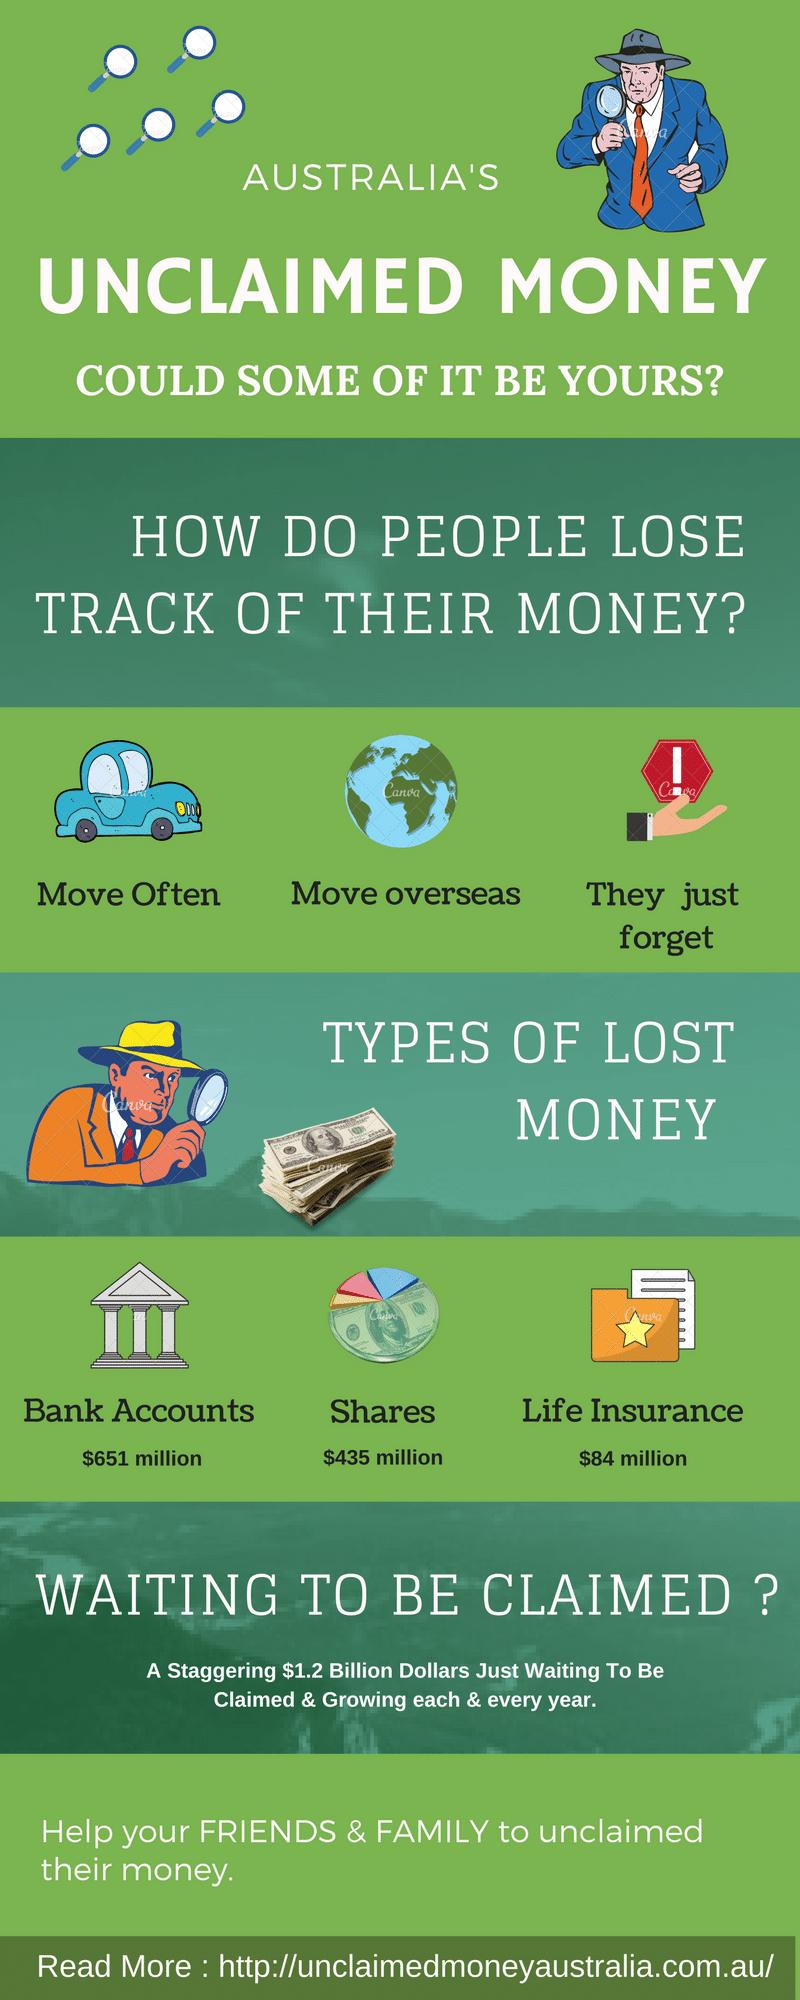
Life insurance policies are designed to provide financial security to beneficiaries upon the policyholder’s death. However, a significant number of these policies go unclaimed, leaving potential benefits untapped. Understanding what happens to these unclaimed life insurance policies is crucial for policyholders, beneficiaries, and insurers alike. This article delves into the reasons behind unclaimed policies, the processes in place to identify and locate beneficiaries, and the eventual fate of these funds. By exploring the mechanisms and challenges associated with unclaimed life insurance, we aim to shed light on an often-overlooked aspect of financial planning and estate management.
Understanding the Fate of Unclaimed Life Insurance Policies
When a life insurance policy goes unclaimed, the fate of the benefits is not as straightforward as one might assume. Insurance companies are required to make reasonable efforts to contact beneficiaries; however, if they are unable to do so, the funds often enter a state known as escheatment. This process involves the transfer of the unclaimed money to the state government, where it is held in trust for the rightful beneficiaries. Each state has its own set of rules and timeframes governing this process, typically ranging from three to five years after the policyholder’s death.
For those wondering about the steps to retrieve unclaimed life insurance benefits, it usually involves a series of actions that can be initiated by potential beneficiaries:
- Contact the state’s unclaimed property office to check for any transferred benefits.
- Utilize online databases such as the National Association of Insurance Commissioners (NAIC) to search for policies.
- Provide necessary documentation, such as a death certificate and proof of relationship, to claim the funds.
It is essential for policyholders to keep their beneficiary information up to date to avoid complications and ensure their loved ones receive the intended financial support.
Legal and Financial Implications of Unclaimed Policies
When life insurance policies go unclaimed, there are significant legal and financial considerations that can affect both beneficiaries and insurers. One primary legal aspect involves the responsibility of insurers to actively search for beneficiaries. In many jurisdictions, there are regulations that require insurance companies to make reasonable efforts to locate beneficiaries, which may include using databases and other tools to identify and contact them. Failure to comply with these regulations can result in penalties for the insurers.
From a financial perspective, unclaimed life insurance policies can become part of the state’s unclaimed property fund. States often have escheat laws, which mandate that after a certain period, usually ranging from three to five years, unclaimed benefits must be transferred to the state. Financial implications include:
- Loss of benefits for beneficiaries who are unaware of their entitlement.
- Increased administrative costs for insurers as they manage unclaimed funds and comply with state regulations.
- Potential tax implications for beneficiaries who eventually claim the benefits, as the funds might be considered taxable income depending on the jurisdiction.
Thus, it is crucial for policyholders to regularly update their beneficiaries and contact information, ensuring their loved ones can access the financial protection intended for them.
Strategies for Locating and Claiming Unclaimed Life Insurance
Finding and claiming unclaimed life insurance can be a meticulous process, but with the right strategies, it becomes more manageable. Start by checking with the National Association of Insurance Commissioners (NAIC), which offers a free online tool to help you locate lost policies. It’s also worthwhile to reach out to the state insurance department where the policy was purchased. Each state may have a database of unclaimed funds, which could include unclaimed life insurance benefits.
- Review personal records: Look through financial documents, bank statements, and tax returns for any indication of premium payments or insurance-related communications.
- Contact the deceased’s financial advisor or attorney: They might have insights into any life insurance policies or know the companies involved.
- Use online search services: Some websites specialize in finding lost life insurance policies, often for a fee. Ensure you use reputable services to protect your personal information.
Persistence and thoroughness are key in the search process. By employing these strategies, you increase your chances of locating and claiming any unclaimed life insurance benefits that may be due.
Preventative Measures to Ensure Your Policy is Claimed
- Maintain Accurate Records: Keep your personal and policy information updated with your insurance provider. Any changes in your address, marital status, or contact information should be promptly communicated to avoid complications.
- Inform Beneficiaries: Ensure your beneficiaries are aware of the policy and its details. Share necessary documents and the insurer’s contact information to facilitate a smooth claims process.
- Regularly Review Your Policy: Periodically review your policy details and beneficiaries to ensure they align with your current wishes and life circumstances.
- Leverage Technology: Utilize digital tools and apps offered by insurers to keep track of your policy status and receive timely reminders for premium payments.
- Consult with a Financial Advisor: A professional can help you navigate complex policies and ensure all aspects are covered, minimizing the risk of unclaimed benefits.
By adopting these strategies, policyholders can significantly reduce the likelihood of their life insurance benefits going unclaimed, providing peace of mind for both themselves and their loved ones.