


In the intricate tapestry of modern healthcare, where choices abound and clarity often seems just out of reach, one question persistently nags at the minds of many: Are High Deductible Health Plans (HDHPs) a boon or a bane? As we stand at the crossroads of fiscal prudence and well-being, the allure of lower monthly premiums entices us like a siren’s call. Yet, beneath this veneer of savings lies a labyrinth of potential risks that could ensnare the unwary. This article delves into the dual nature of HDHPs, unraveling whether these plans are the financial panacea they promise to be, or if they are stealthily undermining the very essence of our health. Join us as we navigate this complex landscape, empowering you with insights to make informed decisions that safeguard both your wallet and your well-being.
Understanding the Trade-offs: Financial Savings vs. Healthcare Access
When it comes to choosing a health plan, the allure of high deductible health plans (HDHPs) often lies in their potential for lower monthly premiums, promising more cash in your pocket. However, this financial boon may come with hidden costs that go beyond your wallet. Balancing financial savings with healthcare access is a delicate act, and understanding the trade-offs is crucial. An HDHP might seem appealing when you consider the immediate savings, but what happens when medical expenses arise? Are you prepared to cover a hefty deductible before your insurance kicks in?
It’s essential to weigh the pros and cons of these plans. Consider the following aspects:
- Cost Savings: Lower premiums can be beneficial for those who are generally healthy and do not anticipate frequent medical visits.
- Risk Exposure: High out-of-pocket costs can be a barrier to accessing necessary healthcare, potentially leading to delayed treatment or financial strain.
- Preventive Care: Many HDHPs cover preventive services at no cost, but anything beyond that can quickly add up.
Ultimately, the decision to choose an HDHP should be made after careful consideration of your health needs and financial situation. While these plans can be a strategic choice for some, they might not be the best fit for everyone. It’s about finding the right balance between saving money and ensuring your health needs are adequately met.
Navigating Medical Costs: Strategies for Maximizing Your High Deductible Plan
High Deductible Health Plans (HDHPs) can be a double-edged sword, offering both challenges and opportunities in managing healthcare expenses. Strategizing is key to ensuring you get the most out of your plan while safeguarding your health. One effective approach is to take full advantage of the Health Savings Account (HSA) often paired with HDHPs. This tax-advantaged account allows you to set aside pre-tax dollars for medical expenses, helping you mitigate the impact of high deductibles. Additionally, consider the following strategies:
- Preventive Care: Utilize free preventive services covered by your plan to catch health issues early and avoid costly treatments later.
- Price Comparison: Shop around for the best prices on medications and procedures, as costs can vary significantly between providers.
- Negotiate Bills: Don’t hesitate to negotiate with healthcare providers for discounts or payment plans, especially if facing large bills.
- In-Network Providers: Stick to in-network providers to benefit from negotiated rates and lower out-of-pocket costs.
By taking a proactive approach, you can navigate your high deductible plan with confidence, ensuring it serves as a financial ally rather than a burden. Remember, the key is to be informed and engaged in your healthcare decisions.
Balancing Act: When to Opt for Preventative Care and Emergency Services
In the intricate dance of healthcare choices, understanding when to prioritize preventative care over emergency services is crucial, especially when navigating the terrain of high deductible health plans (HDHPs). These plans often entice with lower monthly premiums but can lead to high out-of-pocket expenses when unexpected medical needs arise. It’s a balancing act that requires strategic foresight.
- Preventative Care: Investing in regular check-ups, screenings, and vaccinations can avert costly health issues down the line. HDHPs typically cover these services at no cost, encouraging proactive health management.
- Emergency Services: While emergencies are unpredictable, having a clear understanding of your plan’s deductible and out-of-pocket maximums can help you prepare financially for unforeseen events.
By weighing these options carefully, you can maintain your health without falling into financial pitfalls, ensuring that your HDHP truly serves its purpose of saving you money without compromising your well-being.
Expert Recommendations: Making Informed Decisions with Your Health Plan
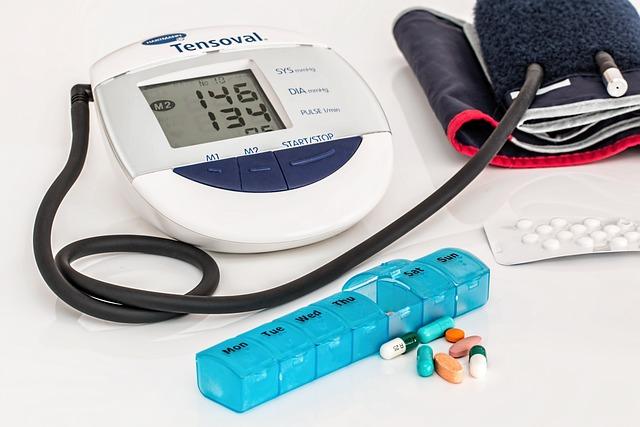
When navigating the landscape of high deductible health plans (HDHPs), expert insights can be invaluable in striking the right balance between cost savings and health security. Healthcare professionals suggest evaluating your personal and family health needs before opting for an HDHP. Consider these key factors:
- Annual Healthcare Usage: If you or your family frequently visit doctors, require regular prescriptions, or anticipate significant medical expenses, the lower premiums of an HDHP might not outweigh the high out-of-pocket costs.
- Emergency Savings: Ensure you have an emergency fund to cover the deductible in case of unexpected medical events. Financial experts recommend having at least the amount of your deductible set aside.
- Health Savings Accounts (HSAs): Take advantage of HSAs if available. These accounts offer tax benefits and can be a strategic way to manage healthcare expenses, but only if you actively contribute and plan for their use.
By aligning your health plan choice with these expert recommendations, you can make informed decisions that prioritize both your financial well-being and health needs.