

Life insurance is a crucial component of financial planning, providing peace of mind and financial security to individuals and their families. However, the process of obtaining life insurance is not as simple as filling out a form and receiving coverage. Central to this process is underwriting, a critical evaluation that determines the terms and conditions of a life insurance policy. Understanding life insurance underwriting is essential for anyone considering a policy, as it directly influences coverage options, premiums, and eligibility. This article delves into the intricacies of life insurance underwriting, explaining its purpose, how it works, and what applicants need to know to navigate the process effectively. By shedding light on this often-overlooked aspect of life insurance, we aim to equip readers with the knowledge necessary to make informed decisions about their coverage needs.
Understanding the Life Insurance Underwriting Process
The life insurance underwriting process is a crucial step that determines the terms and conditions of your policy. It involves a comprehensive evaluation of various factors to assess the risk of insuring you. Underwriters analyze personal and medical information to decide on the premium rates and coverage you qualify for. This process ensures that the policy aligns with your health status and lifestyle, and it typically includes:
- Medical Examination: A thorough health checkup to evaluate your current health status and identify any potential risks.
- Lifestyle Assessment: Consideration of factors such as smoking, alcohol consumption, and hobbies that may influence risk levels.
- Financial Review: Analysis of your financial situation to ensure the policy matches your financial needs and obligations.
Understanding these components helps you prepare better and manage expectations during the underwriting process. By knowing what underwriters look for, you can ensure you present a clear and accurate picture of your health and lifestyle, which can lead to more favorable policy terms.
Factors That Influence Your Underwriting Outcome
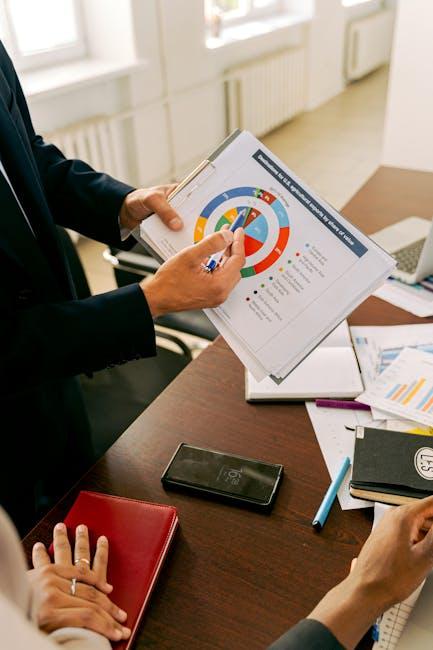
When it comes to life insurance, the underwriting process can feel like navigating a complex maze. Several key factors significantly influence the outcome, and understanding them can better prepare you for what to expect. Age is a primary consideration, as younger applicants generally present lower risk and may receive more favorable terms. Health status is another crucial element, with insurers evaluating your medical history, current conditions, and lifestyle choices such as smoking or high-risk activities. This assessment helps determine your risk level and, consequently, your premium rates.
Beyond personal health, financial stability plays a role in the underwriting decision. Insurers often assess your income and financial obligations to ensure that the policy aligns with your needs and ability to maintain premium payments. Additionally, your occupation might be scrutinized, especially if it involves hazardous duties. Lastly, your family medical history can provide insights into potential hereditary health risks. By being aware of these factors, you can approach the underwriting process with confidence and clarity.
Key Documents Required for Life Insurance Underwriting
When embarking on the journey of securing life insurance, it’s essential to have a clear understanding of the documentation that plays a pivotal role in the underwriting process. Personal identification is fundamental; this typically includes a government-issued ID such as a passport or driver’s license. Furthermore, insurers often require proof of income to evaluate the policyholder’s financial stability, which might involve recent pay stubs or tax returns.
- Medical Records: A comprehensive overview of your medical history is crucial. This may include records from healthcare providers, detailing any pre-existing conditions, treatments, or medications.
- Insurance Application: A detailed application form that captures personal, health, and lifestyle information is necessary to assess risk accurately.
- Beneficiary Information: Details regarding the intended beneficiaries of the policy, including their relationship to the insured and contact information, are required.
These documents collectively enable insurers to assess the level of risk involved and to tailor a policy that aligns with your needs and circumstances. Being well-prepared with these documents can significantly streamline the underwriting process, ensuring a smoother experience for all parties involved.
Tips for Improving Your Underwriting Experience
Enhancing your experience with life insurance underwriting can be achieved by focusing on a few key strategies. First, ensure that all your personal information is accurate and up-to-date. This includes medical records, lifestyle habits, and financial details. Any discrepancies or outdated information can lead to delays or complications in the underwriting process.
- Be proactive: Reach out to your insurance agent or company if you have questions about the process or requirements. Clear communication can prevent misunderstandings and streamline the experience.
- Organize documentation: Having all necessary documents readily available, such as identification, medical records, and financial statements, can significantly speed up the process.
- Understand risk factors: Familiarize yourself with the factors that may affect your underwriting, such as age, health conditions, and lifestyle choices. This awareness can help you prepare better and possibly improve your underwriting outcome.
By implementing these strategies, you can make the underwriting process smoother and more efficient, ultimately leading to a more satisfying life insurance experience.