

In the complex landscape of healthcare, insurance companies play a pivotal role in determining access to medical services and financial protection. A critical and often contentious aspect of this role is the practice of denying coverage based on health risks. As healthcare costs continue to rise and the prevalence of chronic illnesses increases, the ethical implications of such decisions have become a focal point of debate. This article delves into the ethical considerations surrounding the denial of insurance coverage due to health risks, examining the balance between risk management and equitable access to care. By exploring the principles of fairness, responsibility, and the societal impact of these practices, we aim to provide a comprehensive understanding of whether it is justifiable for insurance companies to prioritize financial sustainability over individual health needs.
Understanding the Ethical Dilemmas in Health Risk-Based Insurance Denials
In the complex landscape of health insurance, the practice of denying coverage based on perceived health risks raises profound ethical concerns. Insurers argue that such denials are necessary to maintain financial stability and keep premiums affordable for the majority. However, this approach can lead to significant ethical dilemmas, particularly when it impacts individuals with pre-existing conditions or those genetically predisposed to certain health issues. By excluding these individuals from coverage, insurers may inadvertently exacerbate health inequalities and limit access to necessary medical care.
Key ethical dilemmas include:
- Discrimination: Is it justifiable to deny coverage based on genetic information or pre-existing conditions, potentially marginalizing vulnerable populations?
- Autonomy vs. Paternalism: Should individuals have the right to make their own healthcare choices, or should insurers impose restrictions to control costs?
- Justice and Fairness: How can insurers balance the need for risk management with the ethical obligation to provide equitable access to healthcare?
Addressing these dilemmas requires a nuanced understanding of both ethical principles and the economic realities faced by insurance companies. By fostering dialogue among stakeholders, including policymakers, healthcare providers, and consumer advocates, we can work towards a more equitable insurance system that prioritizes both financial sustainability and ethical responsibility.
Analyzing the Impact of Coverage Denials on Vulnerable Populations
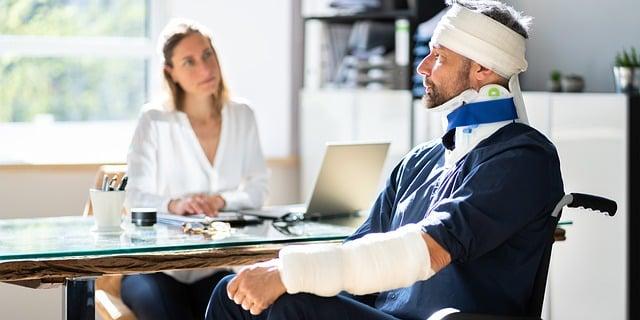
When insurance companies deny coverage based on health risks, it disproportionately affects those already facing significant challenges. Vulnerable populations, including low-income individuals, racial minorities, and those with pre-existing conditions, often find themselves at the intersection of financial instability and health insecurity. This denial of coverage can exacerbate existing inequalities, leading to a cycle of poor health outcomes and increased financial strain. Without adequate insurance, these groups may delay or forgo necessary medical treatments, resulting in more severe health issues down the line.
The ramifications of such denials extend beyond individual health and impact broader societal structures. Consider the following points:
- Increased healthcare costs: Uninsured individuals are more likely to seek emergency care, which is significantly more expensive than regular preventative care.
- Worsening public health: Lack of coverage leads to untreated health conditions, contributing to community-wide health crises.
- Economic implications: As health deteriorates, so does productivity, leading to a ripple effect on the economy through loss of workforce participation.
Addressing the ethical considerations of coverage denials involves balancing risk management with social responsibility. Insurers must evaluate their policies to ensure they do not inadvertently perpetuate cycles of disadvantage and poor health among the most vulnerable.
Exploring Legal Frameworks Governing Insurance Practices
The intricacies of insurance regulation often involve a delicate balance between business interests and consumer protection. In many jurisdictions, the legal frameworks that oversee insurance practices are designed to ensure that companies operate within ethical boundaries while maintaining financial viability. However, the practice of denying coverage based on health risks raises significant ethical concerns. Insurers often justify these decisions by citing the need to manage risk and keep premiums affordable for the broader pool of policyholders. Yet, this practice can lead to a situation where individuals with pre-existing conditions or high health risks are left without necessary coverage.
Under current legal frameworks, several key principles guide insurance practices:
- Fairness and Non-Discrimination: Regulations often require that insurers do not discriminate unfairly against individuals based on health status, gender, or age.
- Transparency: Insurers must provide clear information about policy terms, coverage limits, and the criteria used to assess risk.
- Accountability: There are mechanisms in place to hold insurers accountable for their decisions, often through regulatory bodies or consumer protection agencies.
While these principles aim to create a fair system, the interpretation and implementation of these rules can vary significantly, highlighting the need for ongoing scrutiny and potential reform in the sector.
Recommendations for Ethical Reform in Insurance Coverage Policies
To address the ethical dilemmas posed by insurance coverage denials based on health risks, several reforms can be considered to ensure fairer practices. Firstly, insurance companies should implement transparent assessment criteria. By clearly outlining the factors that influence coverage decisions, insurers can foster trust and reduce the perception of arbitrary denials. This transparency should be complemented by regular audits from independent bodies to ensure compliance and accountability.
- Risk Pooling Strategies: Adopt inclusive risk pooling mechanisms that distribute health risks more evenly, allowing individuals with pre-existing conditions to receive coverage without exorbitant premiums.
- Regulatory Oversight: Strengthen governmental oversight to ensure that insurance companies adhere to ethical standards and do not exploit loopholes that disadvantage vulnerable populations.
- Consumer Advocacy: Support the establishment of consumer advocacy groups that provide resources and assistance to individuals facing unjust denials, empowering them to challenge these decisions effectively.
By integrating these reforms, the insurance industry can move towards a more ethical framework that balances risk management with the moral imperative to provide equitable access to healthcare coverage.